Coordinating Your Will, Trust, and Operating Agreements So They Don’t Conflict
The morning after a sudden tragedy strikes, surviving family members often gather at a kitchen table surrounded by legal documents, assuming that a loved one’s Last Will and Testament solves every financial question. They expect a seamless distribution of personal assets and business equity. Instead, they frequently discover that the deceased founder’s Will promises company shares to a grieving spouse, while the underlying corporate contract explicitly forbids non-working family members from holding voting equity.
When a personal estate plan clashes with a commercial business structure, the resulting legal paralysis can destroy a viable enterprise. The business becomes locked in bitter litigation, bank accounts freeze, and surviving partners are forced into hostile court battles against the very family they meant to protect. Most business owners spend decades building commercial value, yet they fail to align the legal mechanics of their corporate governance with their personal estate planning.
Which Legal Document Supersedes When a Will Conflicts with An Operating Agreement?
Under Maryland law, a business operating agreement generally takes precedence over a Last Will and Testament. Because an operating agreement is a binding contract between entity owners, its provisions governing equity transfers upon death override conflicting instructions written into an individual’s personal estate planning documents.
A common misconception among business owners in Montgomery County is the belief that a Last Will and Testament is the ultimate legal authority over all their possessions. Under state law, a Will only controls probate assets—property owned strictly in an individual’s personal name that does not pass automatically by contract or beneficiary designation. An LLC operating agreement or corporate stockholders’ agreement is a legally binding contract.
When an individual signs an operating agreement, they voluntarily surrender a portion of their personal property rights regarding those specific business units. They agree to abide by the rules established for the entity. If an operating agreement states that upon a member’s death, their equity must be sold back to the company via a mandatory buyout, that contractual obligation is triggered immediately upon death.
If the deceased owner’s Will subsequently states, “I leave my entire business interest to my son,” that provision in the Will is legally unenforceable. The personal representative of the estate cannot transfer the physical shares to the son because the deceased owner signed a contract promising those exact shares to the surviving partners. The contractual obligation established in the operating agreement supersedes the testamentary bequest in the Will.
How Does the Maryland Estates and Trusts Code Handle Non-Probate Assets?
Navigating the distribution of an estate requires a clear understanding of the boundary between probate and non-probate property. The Maryland Estates and Trusts Code governs the administration of estates, granting local Orphans’ Courts jurisdiction over property that passes under a Will or through intestate succession.
Non-probate assets avoid this public and often time-consuming court process entirely. Common examples of non-probate assets include:
-
Real estate held as joint tenants with rights of survivorship
-
Bank accounts with designated pay-on-death (POD) beneficiaries
-
Life insurance policies with named individual beneficiaries
-
Business equity interests subject to binding corporate buy-sell agreements
When an operating agreement dictates the exact transfer pathway for equity upon an owner’s death, that equity interest transfers as a non-probate contractual asset. The Orphans’ Court has no authority to alter the terms of a valid commercial contract. If a business owner in Frederick attempts to use a Will to distribute property that is legally bound by a non-probate corporate contract, the corporate contract prevails, leaving the personal representative powerless to execute the conflicting instructions in the Will.
Can You Transfer Maryland LLC Units Directly into a Living Trust?
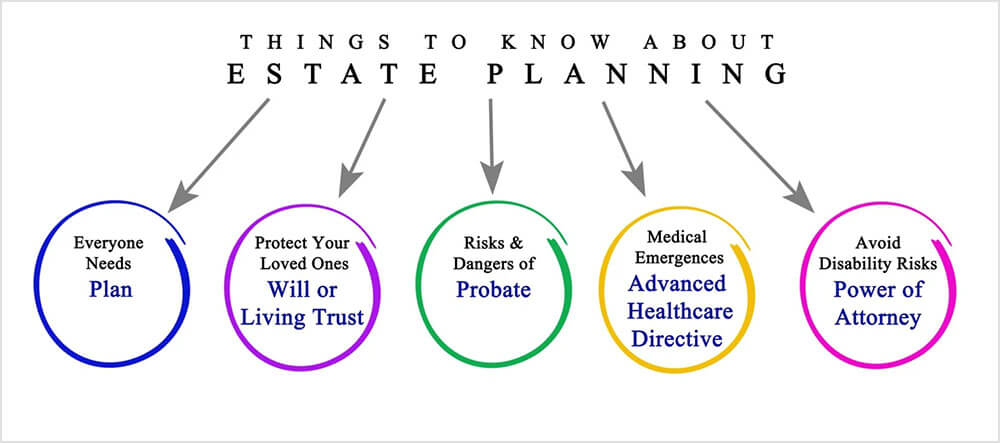
Many business owners utilize revocable living trusts as the central pillar of their estate plan to avoid probate, maintain privacy, and plan for potential incapacity. A trust only controls assets that are formally transferred into its name. To fund a trust with business equity, an owner must execute a formal Assignment of Ownership Interest, transferring their LLC units or corporate stock from their individual name into the name of the trustee.
However, executing a trust assignment without reviewing the company’s foundational documents creates severe legal complications. Under Maryland Code, Corporations and Associations Section 4A-607, an assignment of an LLC interest does not automatically entitle the assignee to participate in the management of the business or exercise voting rights.
Unless the operating agreement explicitly permits the transfer or the remaining members unanimously consent, the trust becomes a mere “assignee.” The trust receives the right to share in profits and distributions, but the trustee holds zero voting authority. If a founder in Bethesda transfers their controlling voting units into a living trust without following the specific assignment protocols outlined in the operating agreement, the trust may be left completely powerless to manage the business operations.
What Happens When Estate Documents Ignore Buy-Sell Provisions?
Ignoring buy-sell provisions creates severe legal paralysis. If a deceased owner’s Will attempts to leave their equity to a spouse, but the company operating agreement mandates a forced cash buyout by surviving partners, the business faces immediate ownership disputes and potential litigation.
A buy-sell agreement is a vital risk-management tool designed to ensure the smooth transition of business ownership upon specific triggering events, such as death, disability, or retirement. It outlines who can purchase the departing owner’s shares, how the purchase price will be calculated, and how the transaction will be funded.
When an estate plan is drafted in a vacuum without cross-referencing the company’s buy-sell provisions, severe structural friction occurs. Common points of document conflict include:
-
Contradictory Transfer Instructions: A Will devises company equity to a surviving spouse, while the operating agreement mandates an immediate buyout by the remaining partners.
-
Valuation Discrepancies: The trust agreement instructs the trustee to hold out for a formal fair-market appraisal, while the buy-sell contract mandates a fixed formula based on historic book value.
-
Payment Term Clashes: The Will demands an immediate lump-sum distribution to satisfy estate taxes, while the corporate buyout agreement allows the company to pay the purchase price over a ten-year promissory note.
-
Unfunded Obligations: The operating agreement requires the surviving partners to buy out the estate, but the company failed to maintain key-person life insurance policies, leaving the business without the cash required to execute the transaction.
These conflicts force surviving partners and grieving families into protracted commercial litigation. The estate’s personal representative is caught between their duty to enforce the Will and the legal reality of the binding corporate contract.
How Do Transfer Restrictions Prevent Unwanted Inheritance?
Transfer restrictions in a corporate agreement legally block owners from bequeathing their shares to outside parties without consent. In Maryland close corporations and LLCs, these clauses protect surviving partners from being forced into business with inexperienced or hostile heirs.
Co-founding a commercial enterprise in Baltimore or Anne Arundel County requires deep trust and shared operational goals. Business partners carefully choose one another based on specific professional skill sets, financial contributions, and industry expertise. They generally do not wish to find themselves in a sudden business partnership with an ex-spouse, an estranged child, or an inexperienced estate executor.
To prevent these scenarios, well-drafted corporate governance documents incorporate strict transfer restrictions. Under Maryland Code, Corporations and Associations Section 4-503, close corporations can impose statutory restrictions on share transfers, rendering any unauthorized transfer void.
Common protective clauses integrated into operating agreements and corporate bylaws include:
-
Right of First Refusal (ROFR): Requires an owner or their estate to offer the shares to the existing company members before transferring them to any outside party or heir.
-
Mandatory Consent Requirements: Mandates that any transfer of voting equity, even to a family trust or immediate relative, must receive prior written approval from a supermajority of the managing members.
-
Permitted Transferee Exceptions: Explicitly defines a narrow group of allowed recipients (such as specific family trusts) that can receive non-voting economic interests without triggering a mandatory buyout.
These contractual guardrails act as a shield for the enterprise. If an owner writes a Will attempting to grant voting shares to an unqualified heir in violation of the operating agreement, these clauses legally block the transfer, preserving operational stability for the surviving partners.
What Are the Critical Steps to Harmonize Your Estate and Business Plans?
Harmonizing your plans requires aligning all beneficiary designations, corporate governance agreements, and trust provisions. Business owners must conduct a thorough legal review to ensure operating agreements authorize trust transfers and that buy-sell funding mechanisms, such as life insurance, match estate tax strategies.
Achieving complete alignment between your commercial interests and personal estate planning requires a systematic review process. Business owners should take proactive steps to ensure their legal architecture functions as an integrated whole:
-
Review Corporate Governance Documents: Examine your existing LLC operating agreement, corporate bylaws, and buy-sell agreements to identify all existing transfer restrictions, buyout triggers, and valuation formulas.
-
Authorize Permitted Transfers: Amend corporate agreements to explicitly permit the transfer of non-voting economic units into revocable living trusts or irrevocable estate-planning vehicles without triggering a forced buyout.
-
Audit Life Insurance Policies: Confirm that key-person and cross-purchase life insurance policies are properly structured, with ownership and beneficiary designations matching the exact terms of the underlying buy-sell agreement.
-
Update Personal Estate Documents: Coordinate the terms of your Last Will and Testament, revocable trust agreements, and financial powers of attorney to explicitly reference and defer to your corporate buy-sell obligations.
-
Execute Formal Assignments: Complete the necessary legal documentation, including formal assignments of interest and updated corporate certificates, to verify that your trust properly holds the intended business units.
Aligning these complex legal mechanisms eliminates ambiguity. It ensures that your business continues operating without disruption while your family receives the full financial value of your life’s work.
Why Should You Review Beneficiary Designations and Capital Accounts?
Beneficiary designations on financial accounts and capital account instructions in an operating agreement operate outside of a Will. If these designations are outdated or contradict your trust instructions, funds may be distributed to ex-spouses or unintended recipients despite your updated estate plan.
A comprehensive estate plan extends beyond Wills, trusts, and operating agreements. It must also encompass non-probate financial mechanisms, including corporate capital accounts, bank pay-on-death designations, and retirement accounts.
When a member invests in a Maryland LLC, the company maintains a specific capital account tracking that owner’s equity contributions, profit allocations, and tax basis. Upon the owner’s death, the operating agreement dictates how that capital account balance is settled. If the corporate agreement states that capital account balances pass directly to surviving business partners, that contractual rule overrides a general clause in a Will leaving “all liquid financial accounts” to a spouse.
Similarly, outdated beneficiary designations on business-funded life insurance policies create massive liabilities. If a company maintains an entity-redemption agreement to buy out a deceased owner’s shares, but the underlying life insurance policy still lists an ex-spouse or a long-retired partner as the named beneficiary, the insurance payout will go to the wrong party. The company will be left without the liquid funds required to execute the mandatory corporate buyout, exposing the business to immediate insolvency or litigation.
When Should Maryland Business Owners Audit Their Governance Documents?
Maryland business owners should audit their corporate governance and estate documents every two to three years, or immediately following major life events. Marriage, divorce, adding a business partner, or significant changes in state tax law necessitate an immediate legal review to prevent conflicting instructions.
Legal documents are not static instruments. As a commercial enterprise grows and personal circumstances evolve, the assumptions built into your original business formation documents may become completely obsolete.
Business owners across the state should initiate a comprehensive legal review upon the occurrence of specific triggering events:
-
Material Shifts in Entity Valuation: If your company’s market value grows significantly, an outdated valuation formula in a decade-old buy-sell agreement could severely underpay your family during a buyout.
-
Changes in Ownership Structure: Admitting a new equity partner, buying out a co-founder, or restructuring corporate share classes requires an immediate update to all transfer restriction clauses.
-
Personal Life Transitions: Events such as marriage, divorce, the birth of a child, or the sudden incapacity of a designated trustee require immediate harmonization across personal and corporate plans.
-
Legislative Changes: Updates to the Maryland Estates and Trusts Code, state inheritance tax thresholds, or federal corporate transparency mandates require structural adjustments to maintain legal compliance.
Conducting regular, structured audits ensures that your corporate agreements and estate planning documents remain fully synchronized, shielding your commercial assets and family from unexpected legal vulnerabilities.
Frequently Asked Questions
Does a living trust protect my Maryland business from probate court?
Yes, formally transferring your business equity into a valid revocable living trust allows those assets to pass to your designated beneficiaries outside of the probate process. However, the trust must be properly funded, and the transfer must comply with all transfer restrictions outlined in your company’s operating agreement.
What happens if my business partners refuse to allow my trust as an owner?
If your operating agreement requires unanimous consent for unit transfers and your partners refuse to approve the assignment to your trust, you cannot force the transfer. In these scenarios, your attorney can help negotiate an amendment to the agreement permitting transfers to specific “permitted family trusts” that restrict voting rights while preserving economic benefits.
Can my spouse claim a share of my Maryland business in probate if my Will excludes them?
Under Maryland’s elective share statute, a surviving spouse has the legal right to claim a statutory percentage of the deceased spouse’s augmented estate, regardless of what the Will states. However, if the business interest is bound by a valid, pre-existing corporate buy-sell agreement, the company may still enforce the buyout, though the cash proceeds from that buyout may be subject to the elective share calculation.
Do I need to update my operating agreement if I create a new trust?
Yes, creating a trust is only the first step. You must review your operating agreement to verify that trust transfers are permitted, execute a formal Assignment of Ownership Interest transferring the units into the trust, and update the company’s official member ledger to reflect the trust as the legal owner.
What is the difference between an economic interest and a voting interest in a Maryland LLC?
An economic interest entitles the holder to receive financial distributions, profit allocations, and tax benefits generated by the company. A voting interest grants the owner management authority to participate in corporate decisions, elect managers, and approve major business transactions. Under Maryland law, these two rights can be unbundled and held separately.